The Executive Trust Briefing / Governance
Your Savings May Be Someone Else’s Work
Organizational trust weakens when one division’s savings become another division’s unpaid workload. Executives need a cost-transfer discipline that distinguishes genuine efficiency from displaced effort before approving budgets, automation programs, or changes to shared enterprise services.
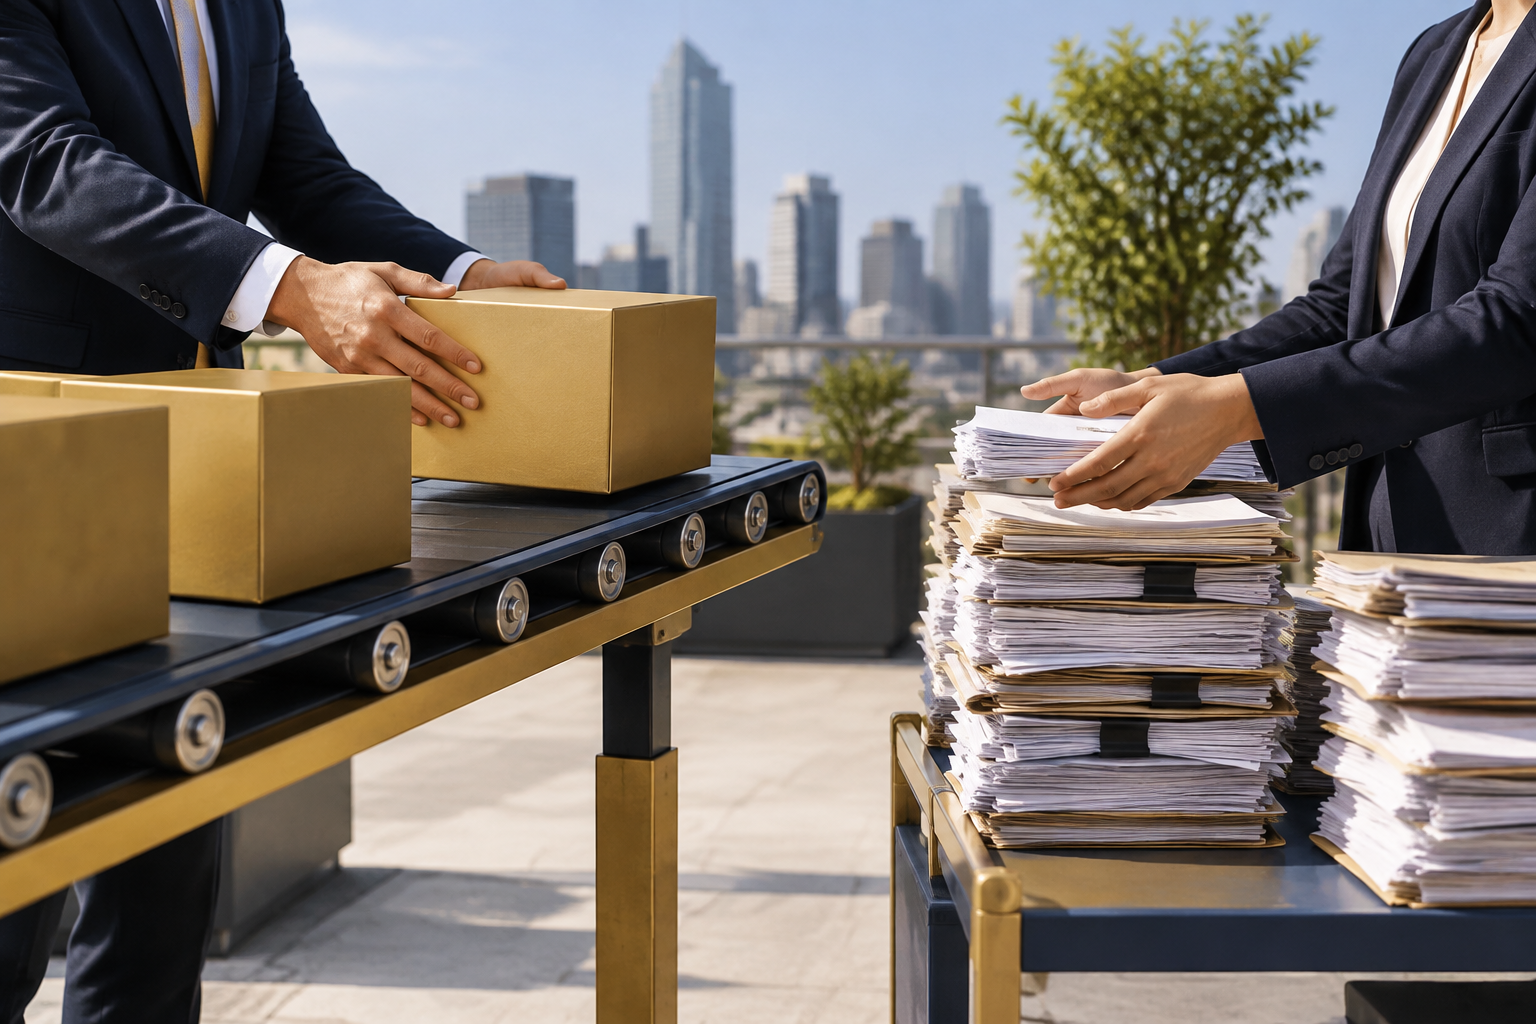
“A budget can make labor invisible without making it disappear; leadership begins by noticing whose hands are still doing the work.”
The Budget Boundary Is Not the Business Boundary
For executives preparing 2027 budgets, the November 14, 2026 issue of The Executive Trust Briefing examines a neglected trust question: whose work makes your savings possible? A division can meet its efficiency target while making the enterprise less efficient. Costs disappear from one ledger because employees elsewhere absorb additional administration, customers perform more troubleshooting, or suppliers carry greater uncertainty. The reported saving may be accurate within the accounting boundary and misleading within the operating reality. Integrity requires leadership to examine both.
Consider a hypothetical shared-services redesign that reduces central support staffing and introduces self-service tools. The sponsoring executive reports lower expenditure. Regional managers now spend time interpreting instructions, resolving exceptions, and correcting submissions. Nothing about self-service makes this outcome inevitable; a well-designed service may genuinely remove work. The trust problem arises when the approval process counts the sponsor’s savings but treats everyone else’s added effort as free. Teams then learn that cooperation can mean accepting costs they neither authorized nor budgeted.
Make the Receiving Side Part of the Calculation
An efficiency proposal should describe where work goes, not merely which expenditure stops. Ask for the tasks eliminated, the tasks automated, and the tasks transferred, with explicit assumptions about frequency, complexity, and exception handling. Estimates will be imperfect. Their value lies in making the claim testable before a budget reduction becomes an irreversible staffing decision. Finance should distinguish cash savings from capacity released and effort displaced. These are different outcomes, and labeling them accurately is a governance obligation rather than an analytical refinement.
The receiving executive needs a formal role in validating those assumptions without gaining an unlimited veto over enterprise change. Where the parties disagree, the investment committee should see both estimates and decide who will fund the uncertainty. This changes the relationship between functions: disagreement becomes a resource-allocation question, not evidence that one team resists progress. For global operations, validation must include local language, regulatory, and service conditions. A transfer that is manageable at headquarters may require specialist intervention in another market.
Recognize Savings Only After the Transfer Is Tested
Approval should establish a provisional benefit, not certify a victory. Before the organization removes the full funding, test the redesigned workflow over a representative operating cycle, including exceptions. Compare total handling effort, service quality, and unresolved work across the contributing and receiving teams. Do not let an attractive enterprise average conceal an unworkable burden on a small function. If the change saves money overall but creates a concentrated disadvantage, leadership should acknowledge that trade-off and finance the capacity required to sustain it.
This discipline connects accountable leadership with everyday relationships. An executive who benefits from another team’s cooperation should remain answerable for the consequences of the redesign, even after launch. The board need not adjudicate every internal transfer; it should expect material efficiency claims to survive an enterprise-wide test. Trust grows when leaders cannot improve their own results simply by moving effort beyond their reporting boundary. Genuine productivity removes unnecessary work. Responsible governance makes it harder to confuse that achievement with relocating the work to someone less able to refuse.
From Insight to Action
Your Leadership Practice
Before approving the next material efficiency proposal, have the CFO require a task-transfer schedule separating eliminated, automated, and reassigned work, with receiving-function estimates of hours and exception costs.
For one proposed shared-service redesign, fund a representative-cycle pilot from the sponsor’s budget and measure handling time, unresolved cases, and service quality in both the sponsoring and receiving functions.
At the next benefits review, require the investment committee to deduct verified downstream operating costs from credited savings and allocate funding to any receiving function carrying an approved additional workload.
0 of 3 Practices Completed
Original editorial commentary inspired by the book’s concepts; not an excerpt from the book. Weekly editions are AI-assisted; the opening quote is drafted with AI for Dr Tyrone Grandison.